

Today’s company is Comstock. The primary business segment is Comstock Metals, a solar panel recycler. If management executes its strategy, they expect this segment alone to generate roughly $450 million in profit within a few years. Against a current market cap of only $230 million, this business provides significant multibagger potential on its own. Protecting downside risk, the company has $55 million in cash and plans to sell up to $350 million in non-core assets this year. Furthermore, they own a 76% stake in Bioleum, a renewable energy venture currently valued at $500 million. While Bioleum is still in the early stages, the plan is to eventually IPO or sell the business, which if successful would most likely be worth many times Comstock’s entire market valuation.
Comstock Metals
The main vision for this company is Comstock Metals, and their business is recycling solar panels. The economics are pretty simple. First, Comstock gets a tipping fee from companies that need to dispose of their panels. Then, they recycle those panels and extract valuable materials like silver to sell back to the market.
The president of Comstock Metals, Dr. Fortunato Villamagna, has over 40 years of experience in hazardous materials and waste-to-energy. You can find more on his background here, while this article provides the context about their industrial plans and the solar recycling industry.
Their goal is to open 6-7 of these facilities across the US over the next few years. Management has shared some estimates for what one facility could do, and while you should always take management numbers with a grain of salt, they work well as a ballpark.
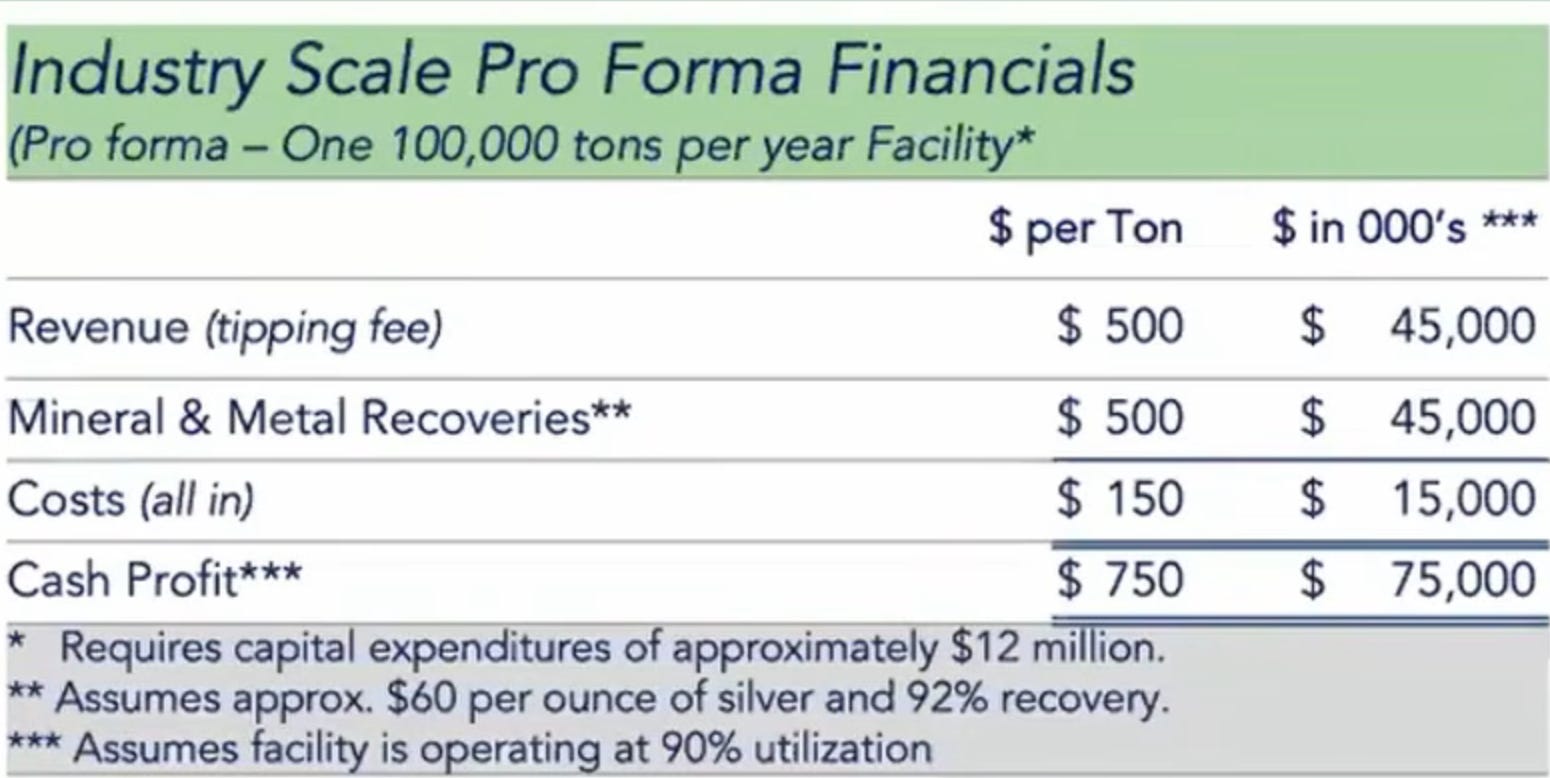
They think that at 90% utilization and $60 silver price, a single facility could generate $90M in revenue and $75M in FCF.
Are these estimates realistic?
The tipping fee income seems solid, and I don't think reality will differ much from their estimates. They have already signed master agreements with major solar companies, they likely have a lot of visibility into that part of the business. The metal recovery is the part that moves around based on market prices. Silver is currently around $77 an ounce, so their $60 estimate actually gives them a decent buffer if the price drops, but I won’t speculate on this.
I believe the real question is if they can actually hit 90% utilization and manage their costs.
End-of-Life Solar Recycling Market
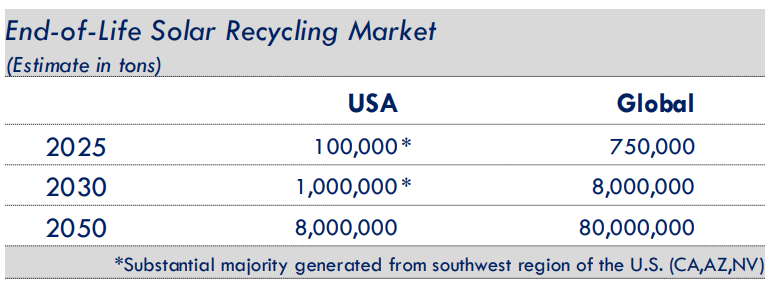
One Comstock facility has the capacity to recycle 100,000 tons a year. To put that in perspective, in 2025 the entire US market for end-of-life solar panels could have been handled by just one of Comstock’s facilities running at 100% utilization. But that market is about to grow ten times over in the next five years. The reason is that the first big wave of global solar installations happened between 2000 and 2010. Since solar panels have a 25 to 30 year lifespan, those early panels are reaching their end right now. Plus, a lot of companies are tearing down 15-year-old panels early just to replace them with new ones that are up to three times more efficient.
Right now, there actually isn’t enough waste out there to hit full utilization, but that is about to change fast. Management said that they expect their first facility to operate at full utilization in 2027. Since the market is still so young, there aren’t many big players yet. With their first industrial scale facility, they’ll become the largest solar panel recycler in the US by capacity. According to the CEO, the biggest energy players don’t even bother talking to anyone else because they need to be sure their partner can actually handle the massive volume coming their way. Comstock is essentially leveraging early/fast expansion to lock in all the major customers before the market even fully exists. The CEO’s vision is to be the absolute market leader, and he has said his ambition is to eventually own 80 to 90 percent of the entire market.
What also sets Comstock apart is that they are the only recycler with a proven and certified 100% zero-landfill process. This is a huge advantage because solar panels are classified as hazardous materials. For companies that need to maintain high ESG scores, Comstock is the safest and cleanest solution.
Valuation
Going back to the numbers, even if we use some quick napkin math and assume they only reach 50% utilization with double the projected costs, one facility would still make $20M in FCF every year. With original numbers, they only need 15% utilization to break even. Plus, it only costs about $12M to build one facility, which is a massive ROI.
If they scale to six facilities by 2030 at 90% utilization, the company would be generating $450M in annual FCF. With 50% utilization and the costs are double, that FCF would still be around $120M.
When you compare that to their current market cap of about $230M, the potential is huge. If the company scales somewhat successfully, the company would have high margins, a strong moat through their existing contracts and still alot of organic growth potential as the market grows. A fair multiple on FCF for a business like this should be atleast 15 to 20x, but the exact number doesn’t even matter that much. If they execute, this could easily be a 10 to 30 bagger.
So why isn’t the stock price reflecting this yet? Well, it is all still only a vision for now. They haven’t actually started running the first full-scale facility yet. That is scheduled for right now in Q2 of 2026, so there is still a lot of execution risk involved. Further, the market doesn’t believe the managements expectations, I’ll get into this later.
On the plus side, they did run a smaller pilot for two years. We know the technology works, so now it is just a matter of seeing if they can scale up to an industry-scale facility, keep the customers coming, and stay cost effective.
Non-core Assets
As I said in the beginning that even if the Comstock Metals would fail, there is still tangible assets that protect that downside. Below you can see managments estimations on their investment.
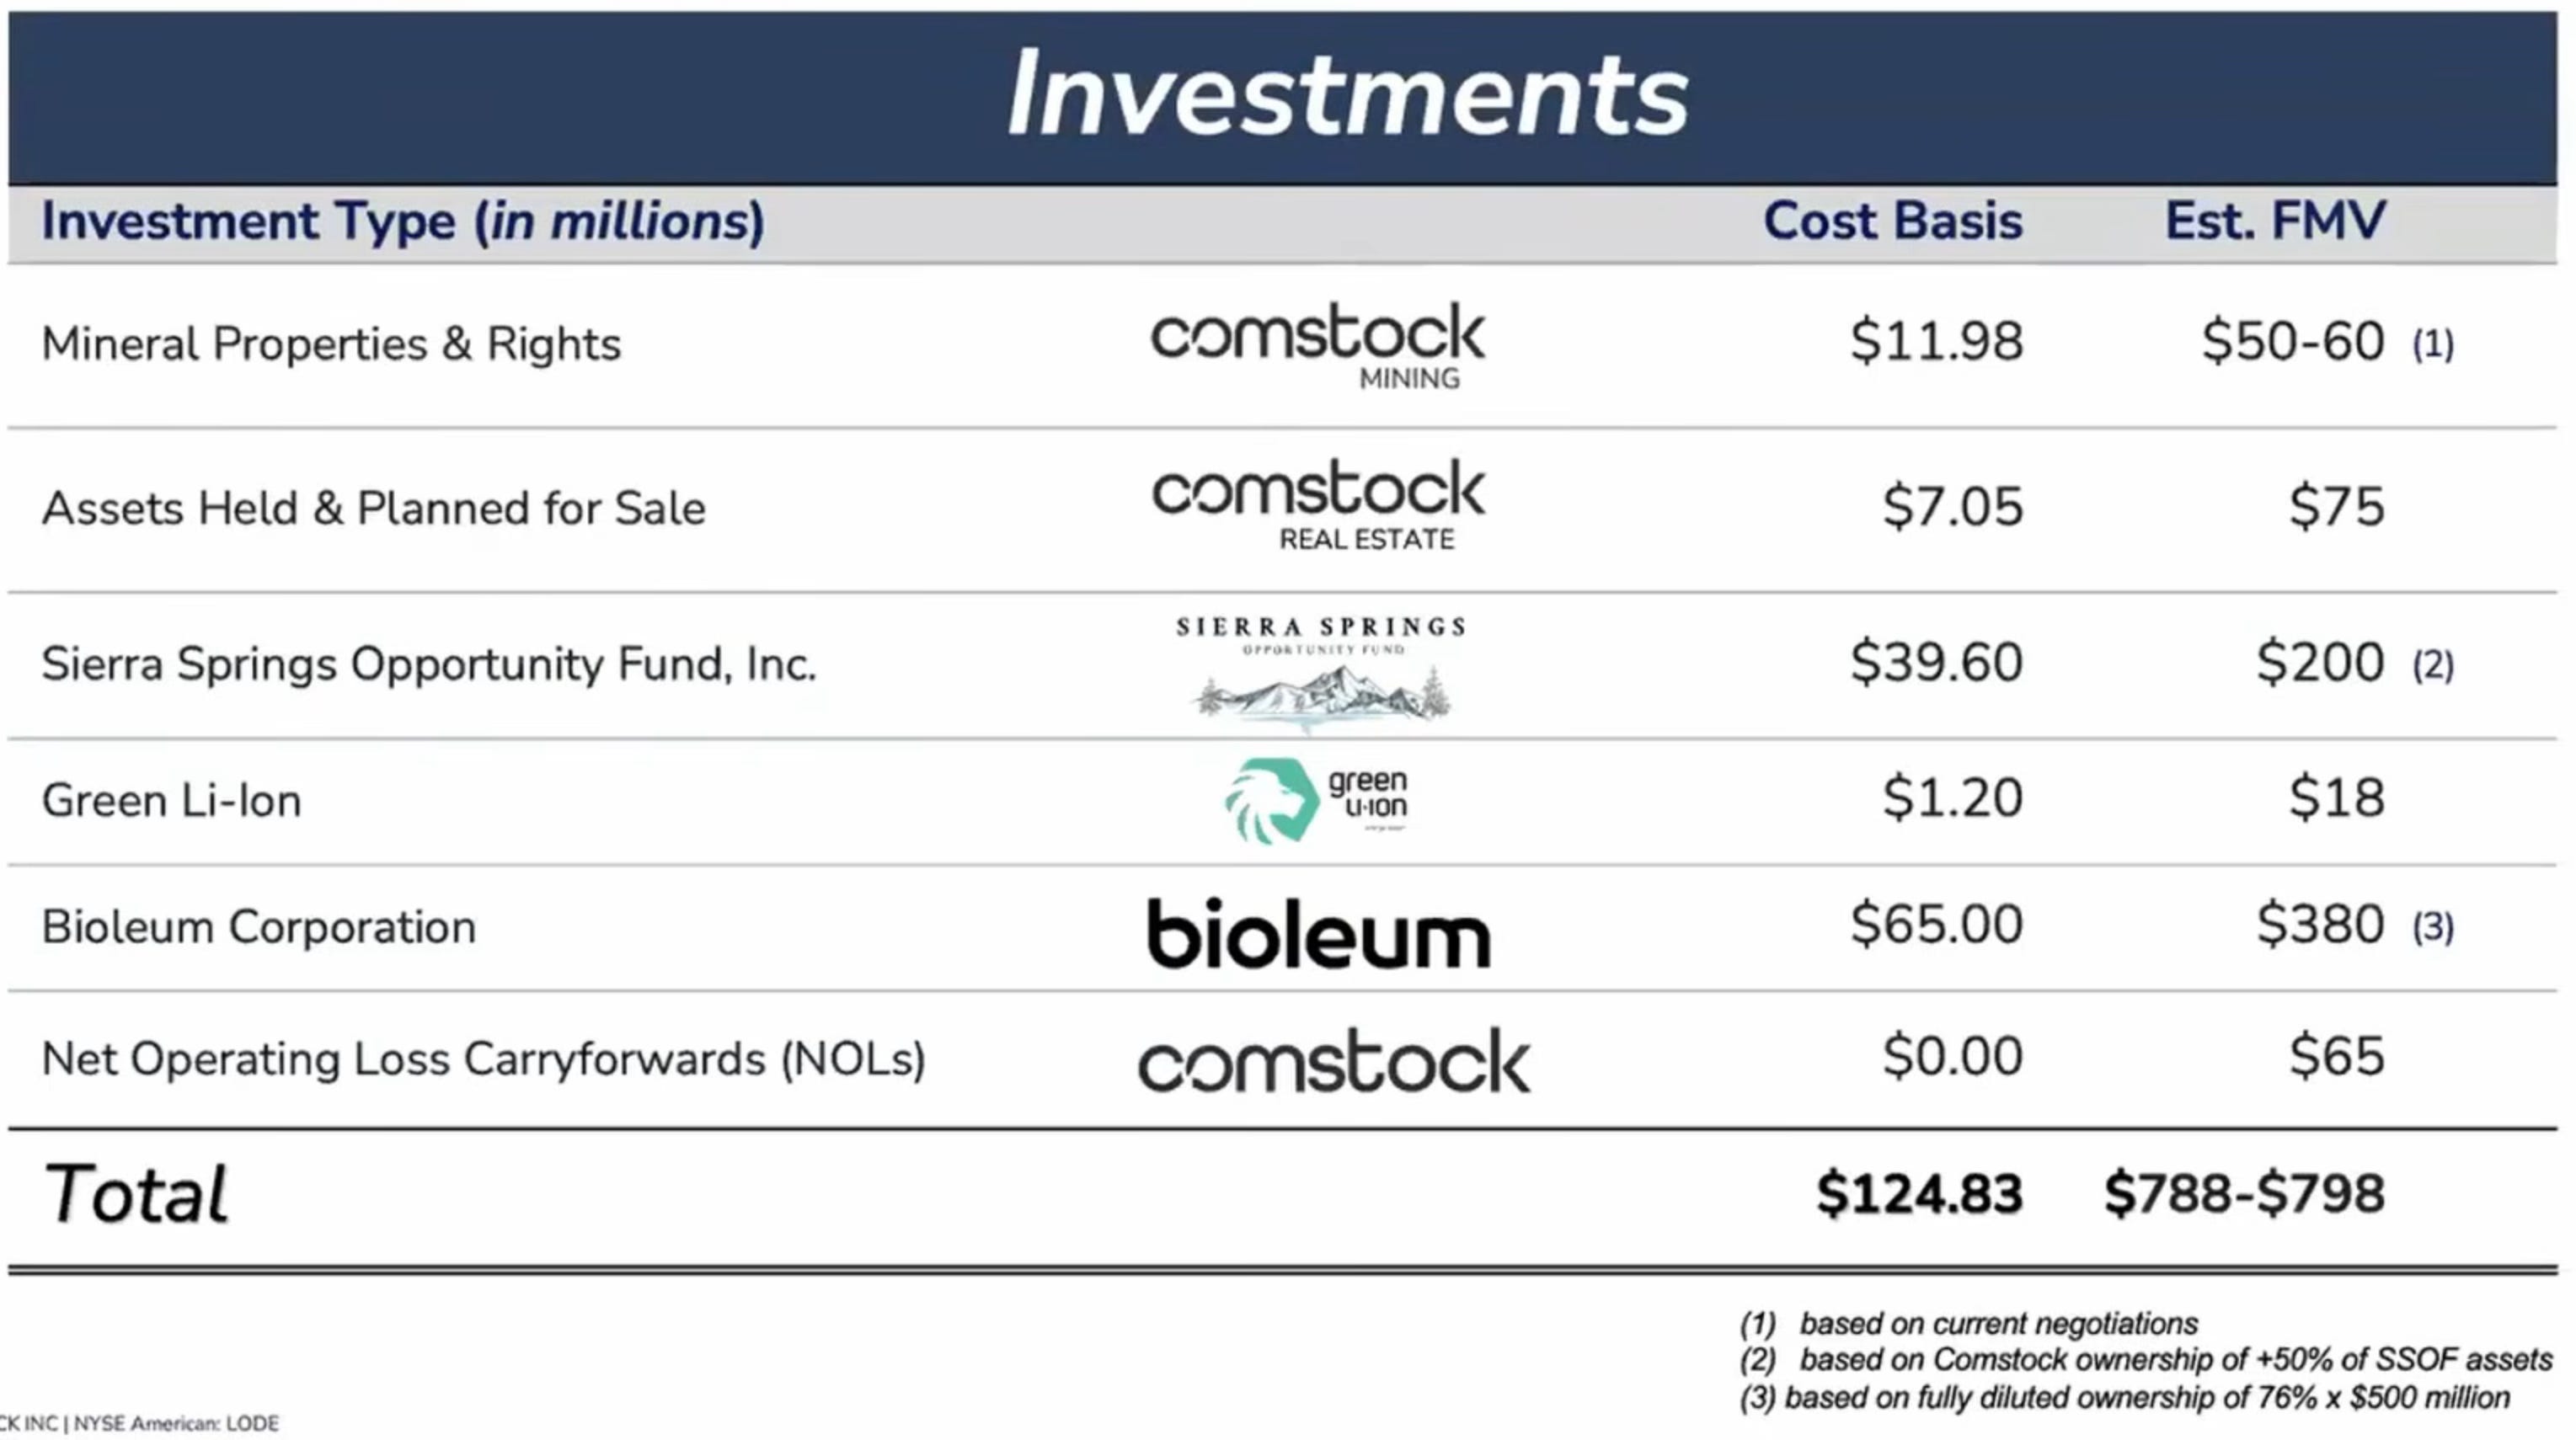
First on the list are the Mineral Properties and Rights. Before Comstock shifted to solar panel recycling, they were primarily a mining company, so these assets are part of that original portfolio in Nevada. Management mentioned in the Q4 2025 earnings call that these properties will likely be sold within the next 75 to 90 days. It is interesting because back in Q3 2025, they estimated the fair value at around $200 million based on high gold and silver prices. Now, based on actual negotiations, they are looking at more like $50 to $60 million. It is a big drop, but it seems much closer to becoming real cash.
The most valuable asset for sale right now is the land in Silver Springs through the Sierra Springs Opportunity Fund (SSOF) and Comstock Real Estate. This area has seen a massive jump in value lately because several of the “Mag 7” tech companies are building data centers there. Management says they have everything ready to close a sale except for the final electricity hookups, and the CEO expects a deal to happen this year. They value this at $200 million based on eventually owning 50% of the fund. Even though their ownership is technically 37% right now, the CEO says it can be over 50% when it is sold. Even if you take that $200 million with a grain of salt and value it much lower, that land plus the Comstock Real Estate worth $75M, the mine worth 50-60M, and $55m on net cash on their balance sheet even with conservative estimates covers the company’s entire market cap.
Bioleum
Then there is Bioleum, which acts like a “free call option” for investors. They own a specialized energy crop called Hexas that grows four to seven times faster than trees. Then using a proprietary refining process, they can produce 100 barrels of renewable fuel per acre every year. This yield is according to them 2x their closest competitor. Fursther, they yield 50x higher than soybean oil and 10x higher than corn ethanol.
Unlike many other biofuels, Hexas does not compete with the food supply because it thrives on marginal land. Instead of depleting the soil like traditional heavy farming, Hexas actually helps restore it. It also has one of the lowest carbon intensity (CI) scores in the industry, sitting around 15 to 16, compared to over 100 for regular petroleum.
That score is important because it allows Bioleum to “stack” its revenue. They sell the fuel at market prices, but because the carbon score is so low, they earn massive government tax credits and sell carbon offsets to other companies. This brings the total value of their product to between $8.00 and $10.00 per gallon. They are effectively getting paid twice, once for the physical fuel and again for the environmental cleanup.
The fact that Marathon Petroleum, a $66 billion giant, has invested alongside partners like MIT and Wells Fargo provides significant validation for the technology. Because Bioleum operates as a separate entity with its own financials, it can’t weigh down Comstock’s financials. However, since Comstock holds a majority stake valued at roughly $380 million, a future IPO or sale could result in a massive payout for shareholders.
Why so cheap?
The main reason the stock trades at such a steep discount is a long history of questionable capital allocation decisions. In the eyes of many long-term investors, management has spent years chasing the “next big thing” while funding those moves by diluting shareholders. This loss of trust prevents the stock price from reflecting the actual value of the assets on the balance sheet.
Before the current focus on solar recycling and Bioleum, the company struggled with a series of ventures. They began as a traditional gold mining operation, but when the mining projects failed to produce the expected cash flow, they pivoted into lithium-ion battery recycling. When that didn’t immediately scale, they moved into renewable fuels and finally solar recycling. Each of these required massive amounts of capital. Because the company hasn’t been yet profitable, that capital was mostly raised by issuing shares.
On a more positive note, the current situation looks to be different from the company’s historical patterns. The CEO has explicitly stated that further dilution is off the table, and the balance sheet supports that claim.
Comstock currently holds roughly $56 million in cash, and management is monetizing up to $350 million in non-core assets. When you consider that the capex requirement for each new solar recycling facility is only about $12 million, it becomes clear that the company has a massive financial cushion.
D-Box and now Comstock. I'm shareholder in both, hope it works out for us.
Nice writeup, ticker not mentioned once though!? Might wanna lead with that next time.